


AST SpaceMobile (ASTS): The $1 Billion Japan Deal, Blacklift Rocket and the Race to Connect Every Smartphone
16 November 2026 | TradeFables | Stock Analysis

Imagine being able to use your ordinary smartphone in the middle of a desert, on a remote mountain or hundreds of miles from the nearest mobile tower.
No special satellite handset. No additional antenna. Just your existing phone connecting to a satellite overhead.
That is the vision behind AST SpaceMobile (NASDAQ: ASTS).
And it is one of the reasons this stock has become such a fascinating—and fiercely debated—investment story.
AST SpaceMobile is attempting to build a global, space-based cellular broadband network that works directly with everyday smartphones.
If successful, the company could help mobile network operators extend connectivity into areas where traditional infrastructure is unavailable or uneconomical.
But there is a catch.
Building a telecommunications network in space requires enormous amounts of capital, highly sophisticated technology, reliable rocket launches and successful commercial partnerships.
And investors are now watching AST SpaceMobile attempt to turn years of technological development into a functioning commercial business.
Following its November 2026 earnings announcement, a major Japanese satellite initiative and the unveiling of its own rocket programme, ASTS has returned to the centre of the space-investing conversation.
The central investment question is no longer simply whether AST SpaceMobile's technology can work. It is whether the company can deploy, finance and monetise that technology at the scale needed to justify its valuation.
Let's examine what is happening, what the numbers reveal and what could determine the stock's future.
1. Why Is ASTS Trending Right Now?
Several important developments have arrived almost simultaneously.
The latest catalysts
First: AST SpaceMobile reported rapidly growing revenue.
Third-quarter 2026 revenue reached $42.3 million, compared with $14.7 million a year earlier.
That represents approximately 187% year-on-year growth.
Second: The company reaffirmed its 2026 revenue guidance.
Management maintained its forecast of $150 million to $200 million for the full year.
Third: AST announced a major Japanese satellite initiative.
The company described approximately $1 billion in non-dilutive support associated with manufacturing and launching satellites for the Japanese market.
Fourth: AST unveiled Blacklift.
The company is developing a reusable rocket intended to carry up to five BlueBird satellites per launch, with initial flights targeted for late 2028.
Fifth: The satellite deployment timetable remains a major focus.
Management is targeting approximately 45 BlueBird satellites in orbit by mid-2027.
These developments help explain why investors are paying attention.
But they also create competing interpretations.
Bullish investors see commercial validation, expanding partnerships and a clearer route towards global coverage.
Sceptical investors see a capital-intensive business attempting to execute several difficult projects simultaneously.
Both perspectives deserve examination.
2. What Does AST SpaceMobile Actually Do?
Traditional mobile networks depend on ground-based infrastructure.
Mobile towers connect phones to telecommunications networks.
In remote regions, installing and maintaining that infrastructure can be expensive or impractical.
AST SpaceMobile wants to complement those networks with satellites.
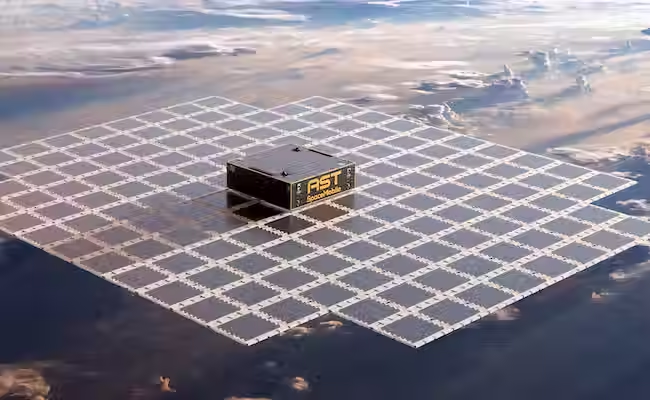
Its BlueBird satellites are designed to communicate directly with compatible everyday smartphones using cellular technology and spectrum arrangements with mobile operators.
This is different from requiring consumers to purchase a dedicated satellite phone.
The intended experience is much closer to using an existing mobile service.
How the business model could work
AST SpaceMobile partners with mobile network operators.
Those operators already have customers, billing systems, spectrum rights and established distribution channels.
AST provides space-based connectivity that can extend the operators' coverage.
Potential revenue models may include wholesale connectivity arrangements, usage-based payments and other commercial structures negotiated with partners.
The precise economics depend on the contracts and markets involved.
For AST, the advantage of this approach is that it does not necessarily need to acquire millions of retail subscribers independently.
It can work through existing telecommunications businesses.
However, an operator partnership is not the same as guaranteed revenue.
Commercial success will depend on network performance, customer adoption, service pricing, revenue-sharing terms and operating costs.

3. The Q3 2026 Earnings Report: Strong Growth, Significant Losses
The latest financial results reveal a company expanding commercially while still investing heavily in its infrastructure.
Financial metric | Q3 2026 | Q3 2025 |
Revenue | $42.3m | $14.7m |
Total operating expenses | $211.0m | $94.4m |
Net loss attributable to common shareholders | $132.4m | $122.9m |
Revenue increased substantially.
But operating expenses also rose, and the company continued to report a significant net loss.
This is not necessarily surprising for a business building a satellite constellation.
However, it demonstrates that AST SpaceMobile is not yet a mature, consistently profitable telecommunications operator.
Investors are largely valuing its potential future network economics rather than its current earnings.
Where is the revenue coming from?
The company attributed third-quarter revenue primarily to gateway deliveries and milestones associated with US Government work.
That distinction is important.
The revenue increase is encouraging, but it should not be interpreted as evidence that a fully deployed global consumer satellite-broadband network is already generating recurring revenue at scale.
The commercial business remains in a transitional phase.
What about 2026 guidance?
Management reaffirmed revenue guidance of $150 million to $200 million.
The midpoint is $175 million.
Investors should monitor whether the company achieves that target and, more importantly, how much future revenue comes from recurring connectivity services rather than equipment deliveries or project milestones.
A growing base of recurring service revenue could eventually make the business easier to value.
4. The $1 Billion Japan Initiative: Why It Matters
One of the most significant announcements involves Japan.
AST SpaceMobile has outlined a satellite initiative supported by approximately $1 billion in non-dilutive funding associated with Japan's Ministry of Internal Affairs and Communications.
The initiative involves Rakuten and the development of a Japanese satellite network.
Reports describe a joint venture in which Rakuten holds 51% of voting rights and AST's Japanese subsidiary holds 49%.
Why investors are excited
Japan is a major telecommunications market with demanding connectivity requirements.
A government-supported satellite initiative could provide AST with an important opportunity to demonstrate its technology and commercial model.
It could also strengthen the company's credibility when negotiating with other governments and mobile network operators.
Most importantly, the announced funding is described as non-dilutive.
That means the arrangement is not presented as a conventional issuance of new AST common shares to raise the equivalent amount.
But there is an important qualification.
Non-dilutive funding is not necessarily unrestricted cash, guaranteed profit or revenue recognised immediately.
Investors should examine the final contractual arrangements, funding conditions, ownership economics, delivery obligations and timing of payments.
A $1 billion programme can be strategically important without producing $1 billion in immediate profit for AST shareholders.
The bigger implication
If the Japanese initiative progresses successfully, it could serve as a reference model for additional national or regional deployments.
That possibility is attractive.
But it remains an opportunity rather than a proven global commercial outcome.
5. Blacklift: AST SpaceMobile Wants to Build Its Own Rocket
Perhaps the most surprising development is AST's decision to pursue its own launch vehicle.
The company has unveiled Blacklift, a reusable rocket designed to carry up to five BlueBird satellites into low Earth orbit.
Its first flight is targeted for late 2028.
AST has also entered into an approximately $1.3 billion arrangement with Firefly Aerospace involving engine technology, manufacturing rights and engineering support.
Why build a rocket?
Satellite operators depend on launch providers to deliver their spacecraft into orbit.
If launch capacity is constrained, even satellites that have completed manufacturing may have to wait.
That can delay service activation and future revenue.
AST's management has identified launch availability as an important constraint.
Developing an in-house rocket could eventually provide greater control over deployment schedules.
Management has also discussed the possibility of reducing launch costs substantially compared with current market pricing.
Why the plan is controversial
Rocket development is extremely difficult.
Even established aerospace companies encounter delays, failed tests and unexpected engineering costs.
Building a reusable orbital launch system adds an entirely new set of challenges to AST's existing satellite-manufacturing and telecommunications ambitions.
Blacklift is not an operational launch system today.
Its targeted late-2028 debut is a management objective, not a guaranteed date.
The programme will also require substantial additional investment.
That creates an important strategic question:
Will owning a rocket ultimately improve AST's economics, or will developing it consume capital that could otherwise accelerate its satellite network?
The answer depends on execution, development costs, launch reliability and the actual savings achieved.
For now, AST continues to rely on external launch providers.
6. BlueBird Satellites: The Deployment Schedule Investors Must Watch
AST SpaceMobile's investment thesis depends on deploying enough satellites to deliver commercially useful coverage.
The company's November update provided several important milestones.
Satellite group | Reported status or target |
BlueBird 11–13 | Unfolded and operating in orbit |
BlueBird 14–16 | Shipped to Cape Canaveral; awaiting confirmed SpaceX launch timing |
BlueBird 17–19 | Expected shipment by late November 2026; Blue Origin launch targeted for early Q1 2027 |
BlueBird 20–25 | Expected shipments during December 2026 and January 2027 |
Overall constellation | Approximately 45 BlueBird satellites targeted in orbit by mid-2027 |
The company also says it has launch agreements covering more than 100 BlueBird satellites expected to be deployed cumulatively across 2027 and 2028.
These are ambitious targets.
But investors should distinguish satellites under construction, satellites delivered to launch sites, satellites successfully launched and satellites operational in orbit.
They are not interchangeable milestones.
Why launch delays matter financially
A completed satellite may represent substantial capital already invested.
Until it reaches orbit, passes testing and becomes operational, it cannot contribute fully to the intended network.
Delays can therefore push expected revenue further into the future.
They may also increase financing requirements.
This is why satellite deployment is not merely an engineering issue.
It is central to AST's financial model.
7. The Technology Upgrade That Could Change Network Capacity
AST is also developing more advanced satellite technology.
Management says its next-generation ASIC architecture can deliver approximately ten times the processing bandwidth of its earlier in-orbit Block 1 satellites.
The company has moved the planned integration of this technology forward to BlueBird 34.
That matters because the economics of a satellite network depend partly on how much usable capacity each satellite can deliver.
More capacity could support additional users, more data traffic or improved network efficiency.
However, a tenfold improvement in processing bandwidth does not automatically translate into ten times the revenue.
Commercial performance also depends on spectrum availability, coverage, demand, device compatibility, network integration and service quality.
The real test will be how the technology performs when deployed at scale.
8. Government Contracts: An Important Second Opportunity
AST's investment story is no longer limited to consumer mobile connectivity.
The company has also been pursuing US Government applications.
In its November update, AST reported a US Space Force award involving advanced space-based sensing capabilities, with approximately $100 million in associated revenue.
It also reported 16 US Government awards to date.
These activities could broaden the company's potential market.
Government demand may support additional use cases for its satellite technology and manufacturing capabilities.
But investors should distinguish contract awards, maximum contract values, funded obligations and revenue already recognised.
Government projects may also carry specialised technical, security and delivery requirements.
The opportunity is meaningful, but execution and contract economics still matter.
9. The Balance Sheet: Is AST Financially Strong Enough?
AST reported approximately $3.2 billion in cash, cash equivalents and restricted cash at 30 September 2026.
That provides a substantial reported pool of financial resources.
However, investors should not assume the entire amount is freely available for any purpose.
Restricted cash may be subject to contractual or other limitations.
The company also has considerable spending requirements.
Its first nine months of 2026 included approximately $314.5 million of net cash used in operating activities, compared with approximately $136.5 million during the corresponding period in 2025.
And operating cash consumption is only part of the picture.
Satellite manufacturing, launch commitments, ground infrastructure and rocket development can require substantial capital investment.
Why the cash balance alone is insufficient
A company may report billions in cash while also facing billions in future spending commitments.
The relevant question is not simply how much cash AST has today.
It is how much unrestricted liquidity will remain after funding the network, servicing debt and meeting contractual commitments.
Investors should monitor future financing transactions, capital expenditure, debt maturities and potential share issuance.
A strong liquidity position can reduce near-term financial risk.
It does not automatically eliminate long-term funding requirements.
10. Share Dilution: The Risk Existing Investors Should Understand
Capital-intensive growth companies sometimes raise money by issuing new shares.
This can strengthen the balance sheet and help finance expansion.
But it also increases the number of shares outstanding.
AST's reported Class A shares outstanding increased from approximately 285.4 million at the end of 2025 to 300.6 million at 30 September 2026.
That is an increase of roughly 5.3%.
This comparison concerns Class A shares, not a fully diluted count of all economic interests and potential securities.
For investors, the distinction matters.
A company's overall business value can grow while the value attributable to each individual share grows more slowly because the share count has increased.
The correct measure of shareholder value creation is therefore not simply total revenue growth or total enterprise value.
It is the value ultimately attributable to each share.
Investors should monitor the company's complete capital structure, including convertible securities, other share classes, stock-based compensation and any future financing arrangements.
11. The Competition: SpaceX, Starlink and Other Players
AST is not developing its network in isolation.
SpaceX's Starlink is a major participant in satellite communications and direct-to-device connectivity.
Other companies and partnerships are also pursuing satellite-enabled mobile services.
The competitive landscape is evolving rapidly.
AST's potential advantage
AST's strategy focuses on providing cellular broadband connectivity directly to everyday smartphones through relationships with established mobile network operators.
Its large satellite antenna architecture and partner-first model are central to that approach.
The competitive threat
Rivals may have advantages in launch access, manufacturing scale, capital availability, spectrum relationships or existing satellite infrastructure.
SpaceX's vertically integrated launch capabilities are particularly relevant.
AST's Blacklift initiative can be understood partly as an attempt to address its dependence on outside launch providers.
But building that capability will take time.
What actually determines the winner?
Investors should watch:
Reliable service performance.
Coverage and capacity.
Cost per unit of usable network capacity.
Spectrum and regulatory approvals.
Commercial distribution.
Pricing and revenue-sharing economics.
Speed of deployment.
The company with the most exciting technology announcement will not necessarily be the one generating the best shareholder returns.
12. Why ASTS Is So Volatile on Stocktwits
ASTS has several characteristics that can produce dramatic share-price movements.
It operates in an emerging market.
Its long-term revenue potential is difficult to forecast.
Important milestones depend on launch schedules, technical performance and regulatory approvals.
Its valuation can be highly sensitive to changes in expectations.
And the stock has attracted substantial short-selling activity.
A Stocktwits report published on 12 November cited approximately 67.5 million shares sold short, representing roughly 22% of the public float at the time.
High short interest can increase sensitivity to positive news, particularly when short sellers rush to close positions.
But a short squeeze is not guaranteed.
High short interest can also reflect genuine concerns about valuation, financing and execution.
Bank of America recently reduced its reported ASTS price target from $80 to $45 while maintaining a Neutral rating, citing launch and execution concerns.
That illustrates how differently investors can assess the same opportunity.
Some focus on the scale of the potential future market.
Others focus on how much capital, time and technical success will be required to reach it.
A popular stock is not necessarily an undervalued stock. And a heavily shorted stock is not automatically a buying opportunity.
13. How Should Investors Value ASTS?
Traditional valuation methods are difficult to apply to a business that is still developing its commercial network.
A price-to-earnings ratio is not especially informative when the company reports significant losses.
A price-to-sales ratio based on current revenue can also be misleading.
Much of the investment thesis depends on future revenue that has not yet materialised.
Instead, investors should build scenarios.
The bull case
AST deploys satellites broadly in line with its plans.
Commercial service expands across major markets.
Mobile operator partnerships translate into meaningful recurring revenue.
The network achieves attractive utilisation and unit economics.
Government programmes provide additional opportunities.
Blacklift eventually reduces launch costs.
Under this scenario, AST could develop into a significant global satellite-connectivity business.
The base case
The company makes commercial progress, but deployment takes longer than management expects.
Revenue grows, yet operating costs and capital expenditure remain substantial.
Additional financing is required.
AST builds a viable business, but the financial returns take longer to emerge.
The bear case
Launch delays persist.
Commercial adoption is slower than anticipated.
Competition limits pricing or market share.
Rocket development increases spending without delivering timely savings.
Financing becomes more expensive, and shareholder dilution reduces per-share value.
Under this scenario, the company could struggle to justify an optimistic valuation despite possessing valuable technology.
A simplified revenue sensitivity exercise
The following table is entirely hypothetical and is not AST management guidance.
Scenario | Illustrative annual revenue | Illustrative operating margin | Operating income |
Bear | $500m | −20% | −$100m |
Base | $2bn | 15% | $300m |
Bull | $5bn | 30% | $1.5bn |
These are deliberately broad scenarios to demonstrate sensitivity, not predictions for a particular year.
The differences are enormous.
And operating income is not free cash flow.
Interest costs, taxes, working capital, satellite replacement spending and other capital requirements could materially affect the cash ultimately available to shareholders.
Before assigning a share-price target, an investor would also need to estimate the timing of these outcomes, financing requirements, future share count, net debt and an appropriate valuation multiple.
That uncertainty is precisely why ASTS can be such a volatile stock.
14. The Five Catalysts I Would Watch Next
1. Commercial service activation
Management is targeting initial intermittent nationwide coverage in key markets before the end of 2026.
The critical issue will be the actual scope, reliability and commercial availability of that service.
2. Confirmed launch dates and successful deployments
Watch the progress of BlueBird 14–25 and whether the company remains on course for approximately 45 satellites in orbit by mid-2027.
3. Evidence of recurring commercial revenue
Future reports should help investors distinguish network-service revenue from equipment deliveries and government milestones.
4. Capital expenditure and financing
Monitor whether planned spending rises, how the company funds Blacklift and the satellite constellation, and whether additional financing affects existing shareholders.
5. Blacklift development milestones
Engine testing, manufacturing progress, programme spending and credible launch readiness will be important indicators.
The stock may react strongly to announcements, but investors should focus on whether those announcements improve the company's probability of achieving sustainable cash generation.
15. What Could Go Wrong?
Every compelling growth story has risks.
For AST, several are particularly important.
Technical risk: Satellite hardware, software or network integration may not perform as expected at scale.
Launch risk: Delays or failures could disrupt deployment and commercial timelines.
Financing risk: Spending requirements may exceed available resources or make additional capital raising necessary.
Commercial risk: Network operators and customers may adopt the service more slowly than anticipated.
Competitive risk: Rival networks could improve their technology, pricing or market access.
Regulatory risk: Spectrum use and service authorisations vary across jurisdictions.
Execution risk: Building satellites, deploying a global network and developing a reusable rocket are individually difficult undertakings.
Valuation risk: Even substantial operational success may not produce attractive shareholder returns if too much future growth is already reflected in the share price.
These risks do not invalidate the investment thesis.
They determine how much uncertainty an investor must be willing to accept.
The TradeFables ASTS Investor Checklist
Before buying or adding to ASTS, ask:
Do I understand how AST expects to earn recurring revenue?
Am I distinguishing commercial milestones from fully operational services?
How many satellites are actually operating in orbit?
Are launch and manufacturing milestones being achieved?
Does the Japan initiative improve AST's economic position under its actual contractual terms?
How much unrestricted liquidity does AST have?
What future capital expenditure is required?
Could Blacklift development delay other priorities?
Are customer partnerships producing recognised revenue?
What advantages does AST have over competing satellite networks?
Could future share issuance dilute my ownership?
What assumptions would justify today's market valuation?
What evidence would prove my investment thesis wrong?
Final Verdict: ASTS Could Be Transformational, but Execution Is Everything
AST SpaceMobile is pursuing one of the most ambitious telecommunications projects in the public markets.
Its vision is straightforward to understand and potentially powerful: extend mobile connectivity through space without requiring consumers to replace their everyday smartphones.
The recent developments are meaningful.
Revenue is growing.
The Japanese initiative provides another potential route to commercial deployment.
Government activity is expanding.
Manufacturing and satellite deployment plans are progressing.
And Blacklift represents an attempt to gain greater control over a critical part of the company's infrastructure.
But investors should resist the temptation to confuse ambition with certainty.
AST is still reporting substantial losses.
Its infrastructure requires considerable capital.
Its commercial network has not yet demonstrated mature, global recurring-revenue economics.
And developing an orbital rocket adds another difficult project to an already demanding execution timetable.
My central takeaway is that ASTS deserves attention not because it is trending, but because the next several quarters could reveal whether its enormous technological ambition is translating into a financially sustainable business.
For bullish investors, the opportunity is the potential emergence of a major new communications network.
For cautious investors, the concern is the amount of execution, capital and future success that may already be reflected in the stock.
Both are reasonable considerations.
The most important question is not whether connecting smartphones directly to satellites would be revolutionary.
It is whether AST SpaceMobile can deliver that revolution at an economic return that ultimately benefits its shareholders.
The technology could change mobile connectivity. The investment outcome will depend on the numbers.
Sources
AST SpaceMobile, Third Quarter 2026 Results and Business Update, 9 November 2026 — https://www.sec.gov/Archives/edgar/data/1780312/000119312526453758/asts-ex99_1.htm
AST SpaceMobile Investor Relations — https://ast-science.com/investors/
Stocktwits, ASTS Short Interest at Two-Year Highs Ahead of Blacklift Event, 12 November 2026.
Stocktwits, Space Stocks Had a Stellar Week, 13 November 2026.
SEC EDGAR, AST SpaceMobile company filings — https://www.sec.gov/edgar/search/
Disclaimer: This article is for educational and informational purposes only and does not constitute personalised investment advice or a recommendation to buy or sell ASTS shares. Financial information is based on publicly reported disclosures available as of 16 November 2026. Forward-looking statements are subject to significant uncertainty. Investing involves risk, including the possible loss of capital.


Comments